Finance · Quantum
Quantum Portfolio Optimization
Solo entry · Winner, Qiskit Fall Fest 2026
QAOA that picks stocks under a sector cap, checked against brute force and classical methods, and run on real IBM hardware.
Key figures
By the numbers
- 3.7-20xvs penalty QAOA (12 stocks)
- 184,756portfolios brute-forced (20 stocks)
The problem
Pick the best set of stocks for a portfolio: high return, low risk, a fixed number of stocks and, at the top level, a cap per sector. The search space grows quickly: 4,096 bitstrings at 12 stocks and 184,756 portfolios at 20.
The approach
QAOA with a mixer that keeps the number of stocks fixed and a start state made only of valid portfolios, so every sample is a valid answer. At 20 stocks a second design keeps both the count and the sector rule inside the circuit. Every result was checked against brute force, and the fast simulator was checked against the real Qiskit circuit.
The result
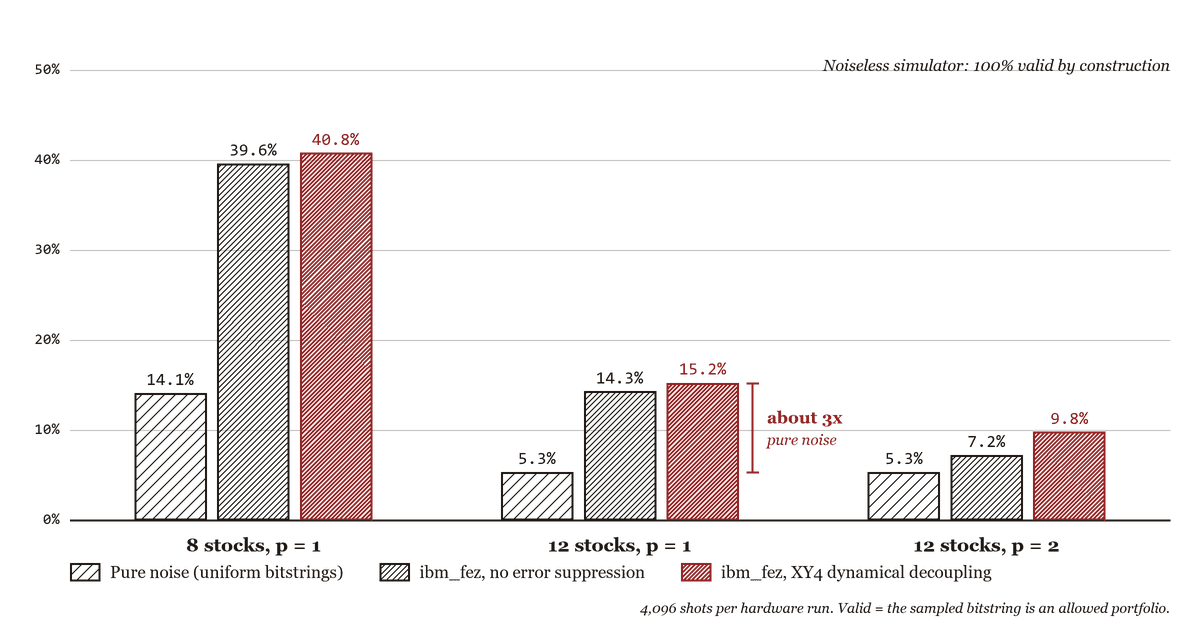
At 12 stocks the mixer beat penalty-based QAOA by 3.7 to 20 times and a random valid pick by 57 times, while greedy search stayed far cheaper, which the write-up says plainly. On the real ibm_fez chip, with error suppression, the 12-stock circuit gave a clear signal above noise.
Built with
- Qiskit
- Python
- NumPy
Figures